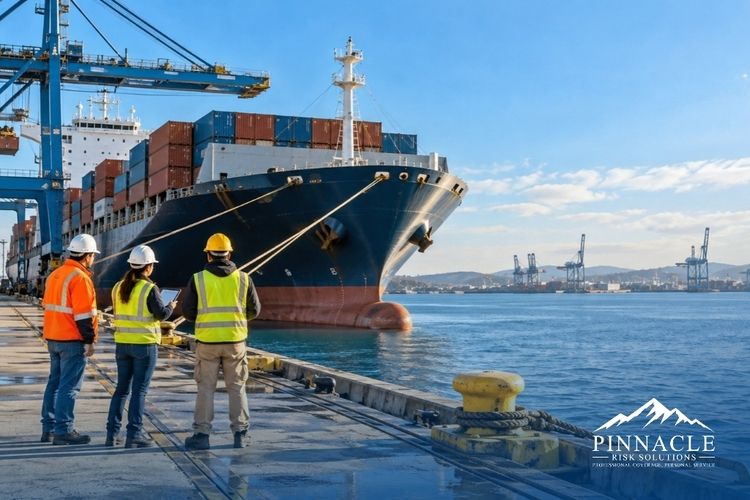
Workers’ compensation may seem straightforward until employees begin working on docks, terminals, shipyards or other areas connected to maritime activity.
In these environments, a standard state workers’ compensation policy may not be enough.
The Longshore and Harbor Workers’ Compensation Act—commonly associated with USL&H coverage—is a federal workers’ compensation law that can apply to certain employees who perform maritime work on navigable waters or in qualifying adjoining areas.
Determining whether the Act applies is not always simple. Coverage generally depends on both the type of work an employee performs and where that work takes place.
For businesses involved in marine construction, shipbuilding, vessel repair, cargo handling, dock work or similar operations, overlooking this exposure could create a serious coverage gap.
What Is USL&H Coverage?
USL&H coverage refers to workers’ compensation protection provided under the Longshore and Harbor Workers’ Compensation Act, often abbreviated as the LHWCA.
The Act provides qualifying employees with benefits for work-related injuries, occupational illnesses and death. Depending on the circumstances, benefits may include:
- Medical treatment
- Disability payments
- Compensation for certain permanent impairments
- Vocational rehabilitation
- Survivor benefits
The program is administered by the U.S. Department of Labor’s Office of Workers’ Compensation Programs.
USL&H coverage is not simply interchangeable with state workers’ compensation. An employee may fall under a federal maritime workers’ compensation framework even when the employer already maintains a state workers’ compensation policy.
The Two Key Questions: Status and Situs
Determining whether an employee may be covered under the Longshore Act often involves two important considerations: status and situs.
The Status Test: What Work Does the Employee Perform?
The status test considers the nature of the employee’s job.
Coverage may apply to employees engaged in maritime work such as:
- Loading or unloading vessels
- Shipbuilding
- Ship repair
- Shipbreaking
- Marine construction
- Dock and terminal operations
- Other activities connected to moving cargo between vessels and land transportation
Job titles alone do not settle the question. The employee’s actual duties matter.
An employee does not necessarily need to perform maritime work during every hour of every shift to create a potential exposure. Even employees with mixed responsibilities may need to be evaluated carefully.
The Situs Test: Where Is the Work Performed?
The situs test considers the employee’s work location.
The Act can apply to qualifying work performed on navigable waters of the United States and in certain adjoining areas customarily used for maritime activities, including:
- Piers
- Wharves
- Docks
- Terminals
- Marine railways
- Shipyards
- Areas used for loading, unloading, building, repairing or dismantling vessels
Being physically close to water does not automatically mean an employee qualifies. Likewise, working on land does not necessarily prevent the Act from applying.
The relationship between the location and maritime activity must be considered alongside the employee’s duties.
Which Businesses Should Pay Attention?
Potential Longshore exposures are not limited to major shipyards or port operators.
Businesses that may need to evaluate their exposure include:
- Marine and waterfront contractors
- Dock builders and repair contractors
- Shipbuilding and vessel-repair companies
- Cargo-handling and stevedoring operations
- Terminal and warehouse operators
- Welding, electrical and mechanical contractors working at maritime locations
- Equipment-maintenance companies serving ports or shipyards
- Staffing companies supplying workers to maritime businesses
- Contractors performing temporary projects on docks, piers or vessels
A company may primarily operate away from the waterfront and still encounter a Longshore exposure through a single contract or temporary assignment.
That is why reviewing work locations, job duties and contractual requirements before a project begins is so important.
What About Employees Working on Vessels?
The Longshore Act generally applies to land-based maritime workers. Masters and members of a vessel’s crew are typically outside its scope and may instead fall under other maritime laws, including the Jones Act.
The distinction between a land-based maritime employee and a vessel crew member can become complicated. An employee’s title, time spent aboard vessels, duties and connection to a particular vessel or fleet may all be relevant.
Businesses should not assume that everyone working near—or even aboard—a vessel belongs in the same insurance category.
Why a Standard Workers’ Compensation Policy may not be enough
A state workers’ compensation policy is designed to satisfy applicable state requirements. It does not automatically guarantee that benefits required under the Longshore Act are covered.
When an employer has a Longshore exposure, the insurance program generally needs to address that exposure specifically through properly structured coverage from an authorized insurance carrier or approved self-insurance arrangement.
If an employer is required to secure Longshore benefits and fails to do so, the consequences can be significant. Potential issues may include uninsured claim costs, penalties, litigation and personal liability in certain circumstances.
The risk may also extend beyond the immediate employer. Under the Act, a contractor can potentially become responsible when a subcontractor fails to secure required coverage.
This makes subcontractor screening and contract review especially important for businesses overseeing maritime projects.
Questions Employers Should Ask Before Work Begins
Before accepting a waterfront or maritime-related project, consider asking:
- Where will employees physically perform the work?
- Will they work on navigable waters, docks, terminals, piers or shipyards?
- Are their duties connected to loading, unloading, building, repairing or dismantling vessels?
- Will employees move between land-based and vessel-based work?
- Are subcontractors being used?
- Do contracts require evidence of USL&H coverage?
- Has the insurance carrier reviewed the actual operations and locations?
- Are payroll and employee classifications being handled correctly?
- Does the current workers’ compensation program specifically address Longshore exposures?
These questions should be answered before employees arrive at the jobsite—not after an injury occurs.
Longshore Exposure Can Change With Your Operations
A business that did not need USL&H coverage last year may develop an exposure this year.
A new contract, customer, worksite or service offering can change the coverage analysis. Even a short-term project at a marina, terminal or shipyard may deserve careful review.
Employers should notify their insurance advisor before:
- Entering maritime-related contracts
- Sending employees to waterfront jobsites
- Beginning vessel-repair or dock work
- Expanding into marine construction
- Hiring maritime subcontractors
- Adding new job duties involving cargo or vessel operations
Early review gives the employer and insurance carrier time to understand the work, determine what information is required and structure the insurance program appropriately.
Protecting Your Business Starts With Understanding the Exposure
Longshore coverage is highly fact-specific. Two employees working for the same company—or even at the same location—may not necessarily be treated the same way.
The safest approach is to evaluate the employee’s duties, worksite, contracts and insurance program together.
At Pinnacle Risk Solutions, we help businesses identify potential workers’ compensation and maritime exposures, coordinate with the appropriate insurance markets and build programs around how employees actually work.
Planning a project near the water or unsure whether your current operations create a Longshore exposure? A proactive coverage review can help identify potential issues before work begins.
Contact Pinnacle Risk Solutions 📞 973-284-0100 🌐 www.pinnrisk.com
This article is provided for general informational purposes only and should not be considered legal advice or a determination of coverage. Longshore eligibility and insurance requirements depend on the specific facts, applicable law and policy terms.